
A practical system for clearer bills and calmer Sundays
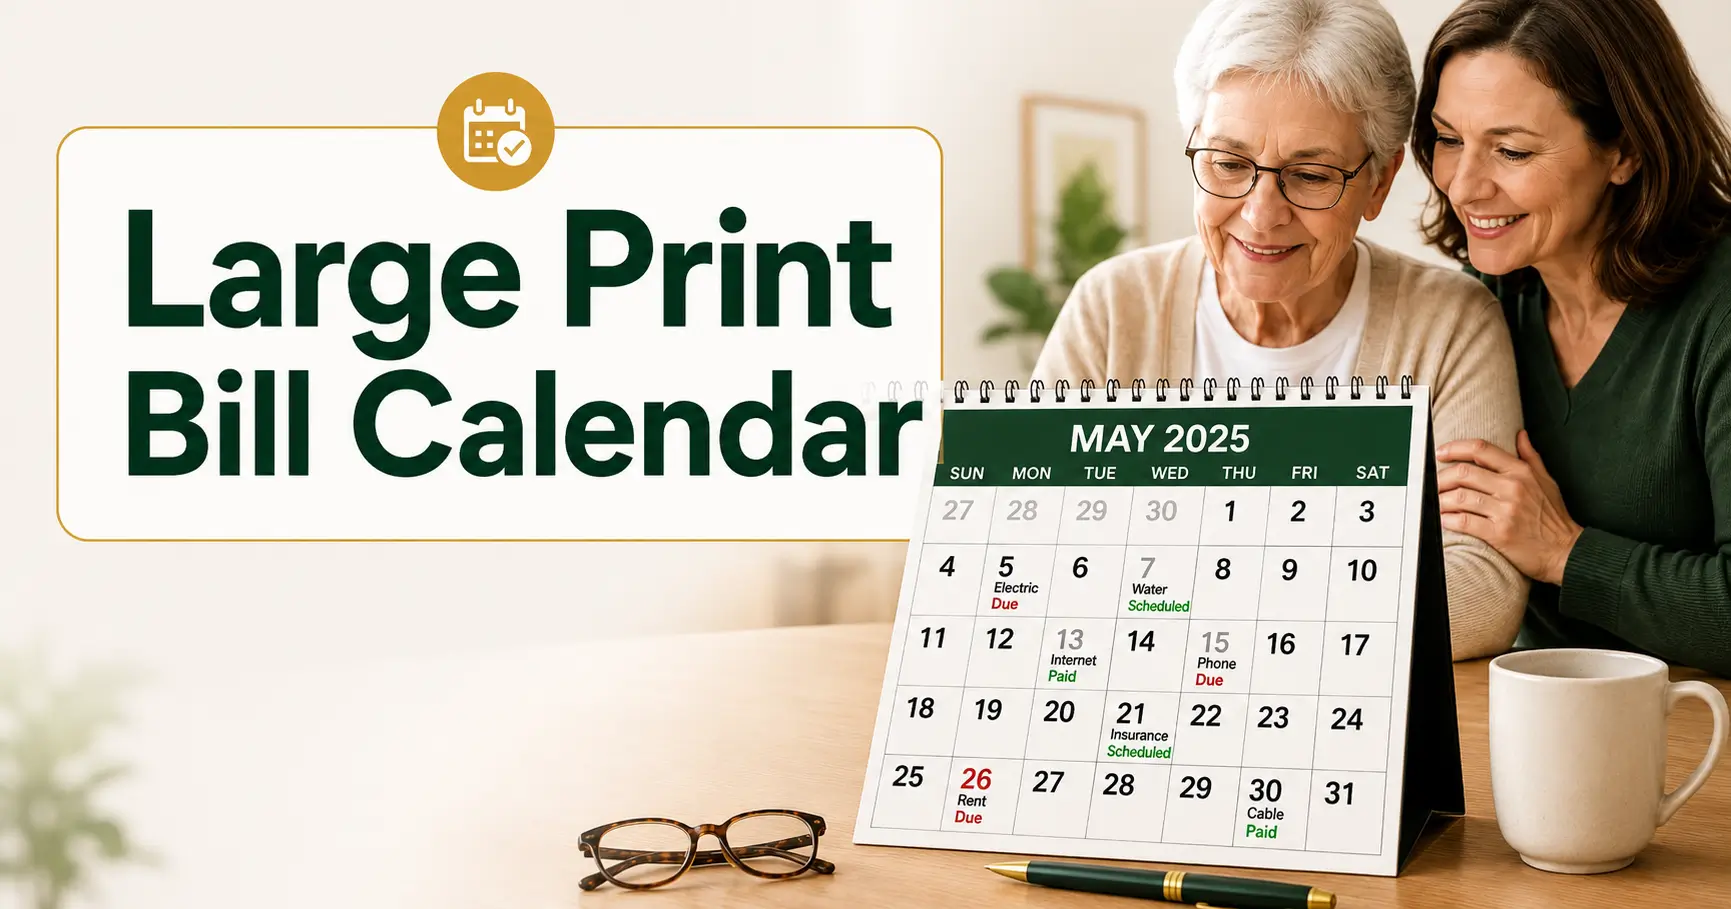
How to Create a Large Print Bill Calendar for Aging Parents
A missed utility bill rarely begins with laziness. More often, the trouble starts with a pale envelope, a cramped statement, an unfamiliar website, or a due date hiding in twelve-point type. One small visual barrier can turn ordinary household paperwork into a month-long game of financial hide-and-seek.
A large print bill calendar can make the next action visible without stripping an older parent of control. The goal is not to place every account detail on the kitchen wall. It is to create a simple, repeatable map showing what is due, what has been arranged, and what has safely cleared.
This guide walks through the full setup, from gathering statements and choosing type sizes to handling autopay, protecting private information, coordinating siblings, and recognizing when a paper calendar is no longer enough. You can build the first test month with a printer, a marker, and about fifteen quiet minutes.
See the next step
Separate bills that are due, scheduled, and fully paid.
Reduce visual strain
Use readable print, clean spacing, and familiar bill names.
Preserve independence
Support your parent’s routine instead of quietly replacing it.
The best bill calendar is not the one with the most information. It is the one that makes the correct next action unmistakable. 📅
Snapshot
Who it is for: Adult children, spouses, and caregivers helping an aging parent who still participates in bill decisions but needs clearer visual cues. What it solves: Missed dates, duplicate payments, autopay confusion, and crowded paperwork. What you will do next: Build one large print test month, agree on a three-status system, and review it together each week.
Table of Contents
Before You Act
A bill calendar is an organizational aid, not financial, legal, medical, or capacity advice. It cannot determine whether someone is able to manage money, authorize another person to access accounts, or prevent every scam. Discuss the system with your parent, follow bank and account-access rules, and seek qualified help when there are repeated losses, suspected exploitation, major cognitive changes, or questions about legal authority.

Know When a Bill Calendar Is Enough, and When It Is Not
A large print bill calendar works best when the main problem is visibility, organization, or an overly complicated payment routine. It provides a fixed place to look, reduces the need to remember dates, and makes completed tasks easier to verify.
It is less useful when the underlying problem is not the calendar at all. A person who cannot recognize a familiar bill, repeatedly sends money to strangers, forgets that payments were made, or cannot follow a simple status legend may need a broader assessment and a more protective support plan.
A good fit: the routine still works when the information is readable
The calendar is likely to help when your parent can explain where income comes from, identify regular household bills, understand that a bill must be paid, and follow a familiar payment method once the date is easy to see.
- Bills are occasionally missed because print is small or envelopes pile up.
- Checks are written correctly, but preparation starts too close to the due date.
- Autopay transactions are forgotten and sometimes paid twice.
- Your parent wants reminders but still wants to make or approve payments.
- A spouse or sibling needs a shared overview without full access to every account.
Warning signs: the problem is growing beyond print size
One late payment is a nuisance. A pattern of unpaid essentials, unexplained withdrawals, duplicate checks, unopened notices, new “friends” requesting money, or increasing confusion deserves closer attention.
Difficulty managing bills can sometimes accompany changes in memory or judgment, although a missed bill by itself does not establish a medical condition. Write down concrete examples, dates, and consequences, then discuss them respectfully with your parent and, when appropriate, a qualified clinician, attorney, financial professional, bank representative, or local aging service.
Support without taking over
Begin with a plain question: “Would it help if we made the due dates larger and easier to check?” That sounds very different from “You cannot manage this anymore.” The first opens a door. The second may feel like someone changed the locks while your parent was still inside.
Agree on who writes on the calendar, who reviews it, and which decisions remain with your parent. Unless you have proper authorization, helping to organize paperwork does not give you permission to access accounts, sign checks, change beneficiaries, or make financial decisions.
Key takeaway
Use a calendar to compensate for a visibility or routine problem. Do not use it to disguise repeated confusion, suspected fraud, or a need for formal financial support.
Start With the Bill Trail, Not a Blank Calendar
It is tempting to download a handsome template and begin filling boxes. Resist that stationery-shaped siren song. First learn how bills actually move through your parent’s life.
Gather 60 to 90 days of statements, envelopes, bank records, check-register notes, payment emails, and automatic-withdrawal entries. Two or three months usually reveal recurring dates, irregular charges, and the small failure points that a single month can hide.
Collect every bill channel, including the invisible ones
Some households receive electric bills by mail, insurance notices by email, pharmacy balances by text, and subscription charges only through a bank statement. The calendar cannot track a bill nobody remembers exists.
Create one working list with the bill name, ordinary due date, delivery method, payment method, approximate amount pattern, and the person who normally handles it. Keep this list private. The visible calendar will use a much simpler version.
- Housing payment, property charges, or rent
- Electricity, gas, water, trash, phone, and internet
- Insurance premiums
- Credit cards, loans, and other debt payments
- Medical payment plans and recurring care expenses
- Subscriptions, memberships, donations, and service contracts
- Quarterly taxes, annual premiums, and irregular household costs
If paper mail is the bottleneck, use a consistent sorting station before building the calendar. This guide to organizing mail for seniors can help separate bills, records, advertisements, and items needing a family review.
Separate monthly, quarterly, annual, and irregular expenses
A monthly calendar naturally favors monthly bills. Annual insurance premiums and quarterly property charges are easier to forget because they disappear for long stretches, then arrive with the subtlety of a dropped saucepan.
| Bill type | Calendar treatment | Extra safeguard |
|---|---|---|
| Monthly | Place on its usual due or withdrawal date | Carry it forward when preparing the next month |
| Quarterly | Add the payment month in advance | Write a preparation reminder seven to fourteen days earlier |
| Annual | Record the due month on a yearly overview | Add an early reminder to check the renewed amount |
| Irregular | Add only after a statement or confirmed obligation appears | Do not copy estimates forward as if they were final bills |
Read late fees as clues, not character judgments
Look for late charges, returned-payment fees, duplicate payments, or long gaps between the statement date and payment date. These are clues about where the system is failing.
- A bill paid late every month may need an earlier preparation date.
- A check that arrives late may need online payment, telephone payment, or more mailing time.
- A duplicate payment often means the calendar does not distinguish “scheduled” from “paid.”
- A forgotten autopay charge may need a balance-check reminder rather than another due-date reminder.
- A statement repeatedly lost in a paper pile may need a dedicated incoming-bills folder.
60-to-90-day bill audit
- List every recurring payee found in statements and account records.
- Circle late fees, duplicates, and unexpected amount changes.
- Mark each payment method: check, phone, online, or autopay.
- Identify the date action must begin, not only the final due date.
- Confirm which bills your parent wants help reviewing.

Choose a Calendar Format Your Parent Will Actually See
A calendar hidden in a tidy binder is useless to someone who checks the kitchen wall. A wall calendar is equally unhelpful to a parent who pays bills at a desk and never looks at the kitchen schedule.
Choose the format by observing the current routine, not by guessing which design looks most “senior friendly.” The most usable setup often resembles what your parent already trusts, only clearer.
Wall, desk, or binder: match the payment station
| Format | Works well when | Watch for |
|---|---|---|
| Large wall calendar | The calendar is checked daily and the location is reasonably private | Visitors may see financial reminders |
| Desk calendar | Bills are opened and paid at one table or desk | Papers can cover the current week |
| Three-ring binder | Your parent prefers pages, folders, and written records | It must remain open or be checked by routine |
| Monthly sheet on a clipboard | A simple test system is needed with minimal cost | Loose pages can be misplaced |
| Digital calendar plus paper summary | A family member coordinates reminders from another location | Two systems must use identical labels and dates |
Monthly versus weekly: choose by bill density
A monthly grid is usually the clearest choice when bills are predictable and spread across the month. It lets the reader see cash-flow clusters, such as several automatic withdrawals arriving just after a fixed income deposit.
A weekly page can work better when many bills fall within a narrow period, several steps are required, or handwriting needs more room. For example, a mailed insurance check might need three entries: prepare, mail, and confirm receipt.
Families already using a large print appointment calendar may prefer to keep financial reminders on a separate page. Mixing medical visits, birthdays, trash collection, and credit-card dates can turn each square into a crowded little attic. For ideas on preserving a clear appointment system, see this low vision calendar setup for appointments.
Short Story: The Tuesday Envelope Basket
Marian’s daughter first made a beautiful binder with labeled tabs, plastic sleeves, and a printed payment checklist. Marian admired it, thanked her, and placed it on a bookshelf. The electric bill was late the following month.
The problem was not the labels. Marian had paid bills at the kitchen table every Tuesday for nearly forty years. The binder lived in the wrong room and asked her to begin an entirely new ritual.
They tried again. A large monthly sheet went on a clipboard beside Marian’s envelope basket. Tuesday became the review day. Bills marked “Due” stayed in the basket. Bills marked “Scheduled” moved to a yellow folder. Cleared payments received a bold check and went into the filing drawer.
The lesson was pleasantly unglamorous: a modest system placed inside an old habit often beats a perfect system that demands a new one.
Make Large Print Calm, Not Crowded
Large print does not mean enlarging every sentence until the calendar becomes a typographic traffic jam. The page needs a clear hierarchy: date first, bill name second, status third, and optional note last.
Start with readable type, then test at the real viewing distance
There is no single font size that suits every older adult. Reading distance, contrast sensitivity, lighting, glasses, eye conditions, and the amount of text all matter. As a practical starting point, make bill names and status labels substantially larger than ordinary statement print, then test the page where it will actually be used.
Use a plain, familiar typeface with open letter shapes. Avoid narrow fonts, delicate strokes, italics for essential information, and long passages in all capital letters. This guide to the best font size for seniors offers a fuller testing approach for household print.
| Page element | Practical design choice | Reason |
|---|---|---|
| Month and year | Largest text on the page | Confirms that the correct page is in use |
| Calendar dates | Bold and easy to locate | Reduces searching inside each square |
| Bill names | Short, consistent, and highly readable | Prevents unfamiliar abbreviations |
| Status words | Bold text plus a symbol | Works even when color is not perceived clearly |
| Notes | Brief and less visually prominent | Keeps the next action from disappearing |
Use contrast and white space as working tools
Black or very dark text on a matte white or warm-white page is a dependable starting point. Avoid pale gray text, glossy paper, patterned backgrounds, and colored ink with weak contrast.
Leave enough empty space for handwriting, correction, and confirmation numbers. Empty space is not wasted real estate. It is where the system breathes.
Use the name your parent recognizes
If your parent calls the local provider “the light bill,” do not label the calendar “regional energy services.” Use the same short name every month. Familiar wording reduces the mental step between seeing the entry and knowing what it means.
- Use “Electric,” not a changing mix of “Power,” “Utility,” and the provider’s initials.
- Use “Visa ending 42,” not a full card number.
- Use “Home Insurance,” not a lengthy policy description.
- Use “Internet Autopay,” not only the company name.
- Use the same wording on the calendar, envelope folder, and private bill list.
Do not make the calendar compensate for every reading task
The calendar should show the action clearly, but statements may still require reading glasses, improved task lighting, or magnification. A large calendar cannot make dense account terms readable by magic. Compare practical options in this guide to magnifiers for seniors.
Key takeaway
Print one sample page before buying supplies. Ask your parent to read it from the normal chair, under the normal light, using the pen normally kept nearby.
Build a Three-Status System That Answers “What Happens Next?”
The calendar’s most important job is not displaying due dates. It is showing whether action is still required.
Use three plain-language statuses: Due, Scheduled, and Paid. Each word represents a different point in the payment journey. Collapsing them into one check mark creates the duplicate-payment trap.
Define “Due,” “Scheduled,” and “Paid” before the first bill is entered
- Due: The bill requires action. Payment has not been arranged.
- Scheduled: Payment has been submitted, mailed, or programmed, but it has not yet cleared.
- Paid: The payment has cleared the account or has otherwise been confirmed as completed.
For a mailed check, “Scheduled” begins when the check is mailed. For an online payment, it begins when the transaction is submitted. For autopay, it can begin when the upcoming withdrawal is reviewed and sufficient funds are expected to be available.
Pair words with symbols, not color alone
Color can make a page faster to scan, but it should not carry the entire message. Ink may fade, printers may vary, and some readers cannot reliably distinguish particular colors.
- Due: Open circle ○ plus the word “DUE”
- Scheduled: Arrow → plus the word “SCHEDULED”
- Paid: Check mark ✓ plus the word “PAID”
Print the legend on every page. A status system that must be recalled from memory is not doing enough work.
Record the confirmation date without crowding the box
A payment submitted on the fifth may not leave the account until the seventh. Instead of writing a long transaction history, use a compact notation such as “Sched 5th” and later “Paid 7th.”
Keep lengthy confirmation numbers on the statement, receipt, or secured companion sheet. The wall calendar usually needs the date and status, not the entire digital breadcrumb trail.
The bill calendar loop
1. CAPTURE
Add the confirmed bill or expected autopay date.
2. PLAN
Mark it Due, then set any preparation reminder.
3. CONFIRM
Change it to Scheduled, then Paid after clearing.
4. FILE
Store the statement or receipt in its agreed location.
Show me the nerdy details
The three-status system separates intent from completion. “Scheduled” records that someone initiated the payment. “Paid” records that the intended financial event actually occurred.
That distinction creates a simple reconciliation control. The family can compare scheduled items with bank activity without treating every submitted payment as finished. It also reduces the chance that two helpers both pay the same bill after seeing an unchanged due date.
For higher-risk payments, add a fourth private field outside the visible calendar: the person who initiated or verified the transaction. This is particularly helpful when siblings share responsibilities.
Enter Bills in the Right Order, Then Tame Autopay
Do not begin with every subscription, donation, and occasional expense. Start with the bills whose failure would cause the greatest disruption, then add smaller items after the system feels familiar.
Enter essential bills first
- Housing costs
- Electricity, heat, water, and essential communications
- Insurance premiums
- Required debt payments
- Recurring medical or care obligations
- Subscriptions, memberships, donations, and flexible services
This order keeps the first test page readable. It also directs attention to the payments where a missed date could have the largest practical consequence.
Add preparation dates when payment takes time
The due date is often too late to begin. A check may need to be written, signed, placed in an envelope, stamped, mailed, delivered, and cleared. An online payment may require a phone code or help navigating the account.
For any bill that needs several steps, add a smaller reminder three to ten days earlier, based on the actual process. Label it “Prepare,” “Review,” or “Mail,” rather than repeating the due date twice.
Place autopay on the date money leaves the account
Autopay is a payment method, not an invisibility cloak. Record the expected withdrawal date so your parent can recognize the transaction and avoid paying the same bill manually.
- Write “Phone Autopay” rather than only “Phone.”
- Note the funding account using a safe nickname, such as “Household Checking.”
- Add a balance-check reminder before large withdrawals.
- Review the new statement amount before assuming it matches last month.
- Mark the item Paid only after the withdrawal appears or completion is confirmed.
Use the calendar to catch autopay price creep
Automatic payments are excellent at being punctual. They are also excellent at quietly continuing after promotional pricing ends, service needs change, or a subscription has been forgotten.
Add a small “Review amount” reminder for bills that vary or renew. The task is not to negotiate every charge each month. It is simply to notice when an ordinary payment becomes unfamiliar.
Key takeaway
For autopay, the calendar should answer three questions: When will the money leave, which account will fund it, and has the amount been reviewed?
Protect Financial Privacy Without Making the Calendar Cryptic
A visible calendar should contain enough information to guide action and no more. Convenience does not justify placing the keys to a financial account beside the grocery list.
Never write sensitive access details on the calendar
- Passwords or password hints
- PINs or security answers
- Full account or card numbers
- Bank routing numbers
- Social Security numbers
- Medicare identification numbers
- Complete login instructions
- Copies of signatures
Do not place these details on a wall calendar, inside an unlocked binder, or on a note attached to the computer. A helpful visitor, contractor, delivery person, or casual photograph should not expose financial credentials.
Use masked references only when they prevent confusion
If two cards or policies have similar names, use a short identifier such as “Card ending 42” or “Life Policy B.” The reference should help your parent distinguish bills without revealing a complete account number.
Keep the same identifier in the private filing system. A consistent low vision filing system can make statements and receipts easier to retrieve without placing sensitive details on the public page.
Create a secured companion sheet for operational details
The companion sheet can list the official payee name, customer-service number taken from a verified statement, payment method, billing frequency, safe account nickname, and location of records. Store it in a secured place agreed upon with your parent.
Passwords should be managed separately using an appropriate secured method. Do not disguise them inside the companion sheet with clues that family members can easily decode.
Pause when a bill, caller, or payment instruction is unfamiliar
Do not use a phone number, email link, or payment address merely because it appears in an unexpected message. Compare it with a prior verified statement, the organization’s official website, or a trusted number already on file.
Urgent demands for gift cards, cryptocurrency, cash withdrawals, secrecy, remote computer access, or immediate payment to avoid arrest or account closure are not ordinary bill-management problems. Stop the transaction and seek help.
Turn the Calendar Into a Five-Minute Weekly Routine
A calendar is a static page. The weekly review is what makes it a working system.
Choose one predictable day, preferably connected to an existing routine. Sunday after breakfast, Tuesday when mail is opened, or Friday before grocery shopping can all work. Consistency matters more than the particular day.
Use the same review sequence every week
- Look seven to ten days ahead for bills marked Due.
- Confirm that scheduled checks or electronic payments were submitted.
- Compare completed payments with bank or account activity.
- Change cleared items to Paid and record the date.
- Investigate unfamiliar charges, missing statements, or amount changes.
- File completed paperwork in the agreed location.
Keep the review brief when everything is normal. A system that routinely becomes a forty-minute audit will eventually be avoided by everyone involved.
Keep the conversation supportive, not supervisory
Try questions that preserve participation: “Which of these do you want to handle today?” “Does this amount look familiar?” “Should we mark this as scheduled now?”
Avoid turning the review into an interrogation about every small purchase. The calendar is meant to reduce friction and catch meaningful problems, not to appoint a family detective with a magnifying glass and no lunch break.
Give siblings clear roles before sharing responsibility
Two helpful people can create one duplicate payment very efficiently. Decide who performs each action and who provides backup.
| Role | Primary responsibility | Boundary |
|---|---|---|
| Parent | Reviews, approves, or completes agreed payments | Receives help without unnecessary loss of control |
| Primary helper | Maintains the calendar and follows up on exceptions | Does not exceed legal or account authority |
| Backup helper | Steps in during absence or emergencies | Checks status before initiating payment |
| Reviewer | Periodically checks that the process remains workable | Does not create a second unofficial system |
Five-minute review card
- What is due next?
- What has been scheduled?
- What has cleared?
- What amount or payee looks unfamiliar?
- What needs filing or follow-up?
Compare DIY, Print-Shop, and Paid Bill-Management Options
A useful bill calendar can cost almost nothing. A sheet of paper, a dark marker, and a familiar clipboard may be enough. Paying more becomes reasonable when printing, binding, shared access, or ongoing assistance solves a specific problem.
Good, Better, Best: choose the lowest tier that reliably works
| Setup | What it includes | Relative cost | Best for | Main tradeoff |
|---|---|---|---|---|
| Good: DIY monthly sheet | Home-printed grid, dark pen, three-status legend, envelope folder | Lowest | Testing the idea or managing a small number of bills | Family must create and update the layout |
| Better: customized print setup | Larger paper, durable binder or clipboard, recurring pages, labeled folders | Low to moderate one-time cost | Readers who need more writing room or sturdier materials | Requires careful privacy and storage choices |
| Best-fit paid support | Bill-pay software, daily money management, bookkeeping, or professional coordination | Ongoing fee or service cost | Complex accounts, long-distance caregiving, or repeated administrative errors | Provider screening, authority, privacy, and scope must be confirmed |
A free option is enough when clarity is the only missing piece
Stay with a simple paper system when your parent understands the bills, payment methods remain manageable, and the weekly review catches mistakes before they become costly.
A large print check register may also help when handwritten payment records are difficult to read. Compare paper and digital approaches in these large print check register alternatives.
Paid tools may be worth comparing when coordination is the real problem
A paid bill-management tool or service may be useful when several people need controlled visibility, statements arrive through many channels, bill volume is high, or helpers live far away. The purchase should remove a specific burden, not merely add a glossy dashboard.
- Can the display and printed reports be enlarged?
- Can access be limited by role?
- Does the service show pending versus completed payments?
- How are account credentials stored and protected?
- Can alerts be sent without exposing full account details?
- What happens if a payment fails or the service closes?
- How can records be exported?
- Is telephone support available and easy to understand?
Questions to ask before paying a professional helper
Daily money managers, bookkeepers, care managers, attorneys, accountants, and financial professionals serve different purposes. Clarify exactly what the person will do, what authority is required, how records will be protected, and how fees are calculated.
- Will you organize bills, initiate payments, reconcile accounts, or only provide reminders?
- What credentials, insurance, screening, or professional affiliations can be verified?
- Who has custody of original records?
- How are errors, suspected fraud, and conflicts reported?
- Can the arrangement begin with a limited trial period?
- Will my parent receive clear statements of work completed and fees charged?
- How can services be ended and records returned?
Do not grant broad account access simply because a service appears convenient. Compare the narrowest level of assistance that solves the problem and confirm any legal documents with an appropriate professional.
Common Bill Calendar Mistakes That Create More Work
Most failed calendars are not missing a clever feature. They are carrying too much information, using unclear labels, or asking the family to maintain several competing versions.
| Common mistake | Why it causes trouble | Safer alternative |
|---|---|---|
| Shrinking text to fit every detail | The page becomes technically complete but functionally unreadable | Keep only bill name, date, status, and a brief note |
| Mixing statement dates with due dates | The reader cannot tell when action is required | Use the due or withdrawal date, plus a clearly labeled preparation date |
| Marking a bill paid when submitted | A failed or delayed payment may be overlooked | Use Scheduled until the payment clears |
| Relying only on colored ink | Status may be unclear in low light or with reduced color perception | Pair color with words and symbols |
| Changing abbreviations each month | The reader must relearn the page | Maintain one standard bill-name list |
| Writing account credentials on the calendar | Anyone seeing the page may gain sensitive information | Store operational details separately and securely |
| Using several family calendars | Helpers act on different versions | Designate one source of truth |
| Taking control without discussion | The system may be resisted or hidden | Agree on roles, consent, and review boundaries |
Real-world example: the duplicate payment nobody intended
A daughter sees “Insurance due 12th” on the calendar and pays online on the eighth. She adds a check mark. Her father assumes the check means the bill has been reviewed, not paid, so he mails his usual check on the ninth. The insurer receives two payments.
The problem is not carelessness. The check mark carries two meanings. Replacing it with “Scheduled 8th,” followed by “Paid 10th” after the account clears, removes the ambiguity.
Do not redesign the page after every small complaint
A new system feels unfamiliar during its first week. Collect notes, but wait through one billing cycle before changing anything that is not unsafe or genuinely confusing.
At the end of the month, ask which entries were hard to read, which labels were unclear, and which steps required repeated explanation. Fix those points. Leave the parts that worked quietly alone.
Know when an “organization problem” may be fraud
Unrecognized withdrawals, sudden secrecy, unusual transfers, unpaid essentials despite sufficient funds, or repeated contact from persuasive strangers should not be solved by merely adding another calendar box.
Preserve statements and messages, contact the financial institution through a verified channel, and consider reporting suspected exploitation to the appropriate authorities or local adult protective services.
Key takeaway
When a mistake repeats, change the system before blaming the person. When unfamiliar money movement appears, pause the system and investigate.
FAQ About Large Print Bill Calendars for Aging Parents
What font size is best for a large print bill calendar?
There is no universal best size. Use a noticeably larger size than ordinary document print, choose a plain font with strong contrast, and test the calendar at the actual viewing distance. The smallest essential text should still be comfortable under the room’s normal lighting.
Should bills be listed by due date or by category?
Place bills on the calendar by due date, scheduled-payment date, or expected autopay withdrawal date. Categories are more useful on the private master list or in the filing system. A calendar should answer when action happens, not merely what type of bill it is.
How do you show autopay bills without causing duplicate payments?
Include “Autopay” in the bill name and place it on the expected withdrawal date. Mark it Scheduled after the amount and funding account are reviewed, then mark it Paid when the transaction appears or completion is confirmed.
Is a paper calendar safer than a bill-management app?
Each option has different risks. A visible paper calendar may expose information to visitors, while an app may collect financial data or require secure account access. Use minimal information on paper and compare privacy, access controls, support, and export options before adopting a digital service.
What information should never appear on the calendar?
Do not include passwords, PINs, security answers, full account numbers, routing numbers, Social Security numbers, Medicare identifiers, or detailed login instructions. Use short, masked references only when two similar bills must be distinguished.
How can siblings share bill responsibilities without creating confusion?
Use one calendar as the source of truth, assign one primary helper and one backup, and record who initiated higher-risk payments on a private log. Nobody should submit a payment before checking its current status.
What should you do when a parent refuses help with bills?
Begin with the specific inconvenience rather than a broad judgment about ability. Offer a one-month visibility experiment, such as enlarging due dates or sorting incoming mail. If there are urgent safety, exploitation, or capacity concerns, seek appropriate professional guidance rather than forcing informal access.
How often should the bill calendar be reviewed?
A brief weekly review works for many households. Review more often during the first month, around income-deposit dates, after a hospitalization or move, or when bills and payment methods have recently changed.
Can a bill calendar help document repeated late payments or memory problems?
It can provide dated examples of missed, duplicated, or misunderstood payments, but it cannot diagnose a condition or determine financial capacity. Keep objective notes about what happened and discuss concerning patterns with qualified professionals.
Build One Test Month in the Next 15 Minutes
Do not redesign your parent’s entire financial life tonight. Build one quiet, useful page.
- Take a blank monthly calendar or print a simple grid.
- Add the month and year in the largest text.
- Enter five essential recurring bills using familiar names.
- Write the legend: Due ○, Scheduled →, Paid ✓.
- Add one earlier preparation reminder for any mailed or complicated payment.
- Label autopay entries clearly.
- Remove every sensitive account detail.
- Place the page where bills are normally handled.
- Choose one weekly review day with your parent.
Then stop. Let the page live through a billing cycle. Notice where hands hesitate, where eyes search, and where a label needs explaining twice. Those small moments will tell you more than a stack of elaborate templates.
When the first month ends, keep what worked and remove what did not. A successful large print bill calendar should feel less like a new financial program and more like someone finally turned on the right lamp.
Your one-page promise
Make the date visible, make the status explicit, keep private details private, and review the page with your parent rather than around them.
Last reviewed: 2026-08